For a Sydney landlord, the interest-rate debate becomes practical when the loan repayment leaves the account. A stronger national household balance sheet offers little comfort if a rental property has thin cash reserves, an upcoming repair or a tenant preparing to leave. Understanding the economic argument matters, but so does recognising its limits.
Michael Read’s analysis in the Australian Financial Review on 9 October 2026 asks why household spending has remained resilient under high rates. It offers a useful lens for property investors: if some households can keep spending, the path to lower inflation may be less straightforward. YAY’s view is to plan around the property’s actual cash flow, with rate relief treated as a possibility rather than a requirement.
Why household resilience complicates the inflation story
Read reports that nominal consumer-spending growth had accelerated despite expensive borrowing. His principal economist source, Deutsche Bank macro strategist Lachlan Dynan, argues that deposits, equities and superannuation help explain household resilience. The article puts household debt at about 178 per cent of disposable income, but debt at only 16 per cent of total household assets.
Dynan’s interpretation is that investment income and accumulated wealth can soften the squeeze on spending. This is an economist’s assessment, not a confirmed RBA forecast. The RBA’s January 2025 cash-flow research also provides a useful counterpoint: it found aggregate cash-flow sensitivity broadly stable over the preceding decade, while stressing differences between households.
YAY’s interpretation for investors is that the relevant question is whether demand remains strong enough to slow disinflation. Nominal spending alone cannot answer that: it reflects prices as well as quantities. Persistent spending is a reason to examine the inflation outlook carefully, rather than evidence that a particular rate decision is inevitable.
References: Australian Financial Review · Reserve Bank of Australia
A wealthy household sector can still contain stretched owners
YAY’s reading is that a national balance sheet and a landlord’s bank account answer different questions. Assets and debt are unevenly distributed. A household with substantial savings and modest borrowing may experience the same interest-rate setting very differently from a recent purchaser carrying a large variable-rate loan.
Liquidity matters too. Superannuation is generally retirement capital, subject to access rules, rather than a readily available maintenance fund. Property equity does not automatically pay a mortgage instalment. Shares can fluctuate and selling them may carry consequences. Owners should distinguish money available for current expenses from wealth that is difficult or undesirable to access.
The same distinction applies to tenants. Aggregate resilience does not establish that the household renting your property can absorb another cost increase. A rental strategy should consider the property, comparable listings and tenant circumstances, rather than assuming national wealth translates into stronger local rental demand.
What a longer period of elevated rates could mean
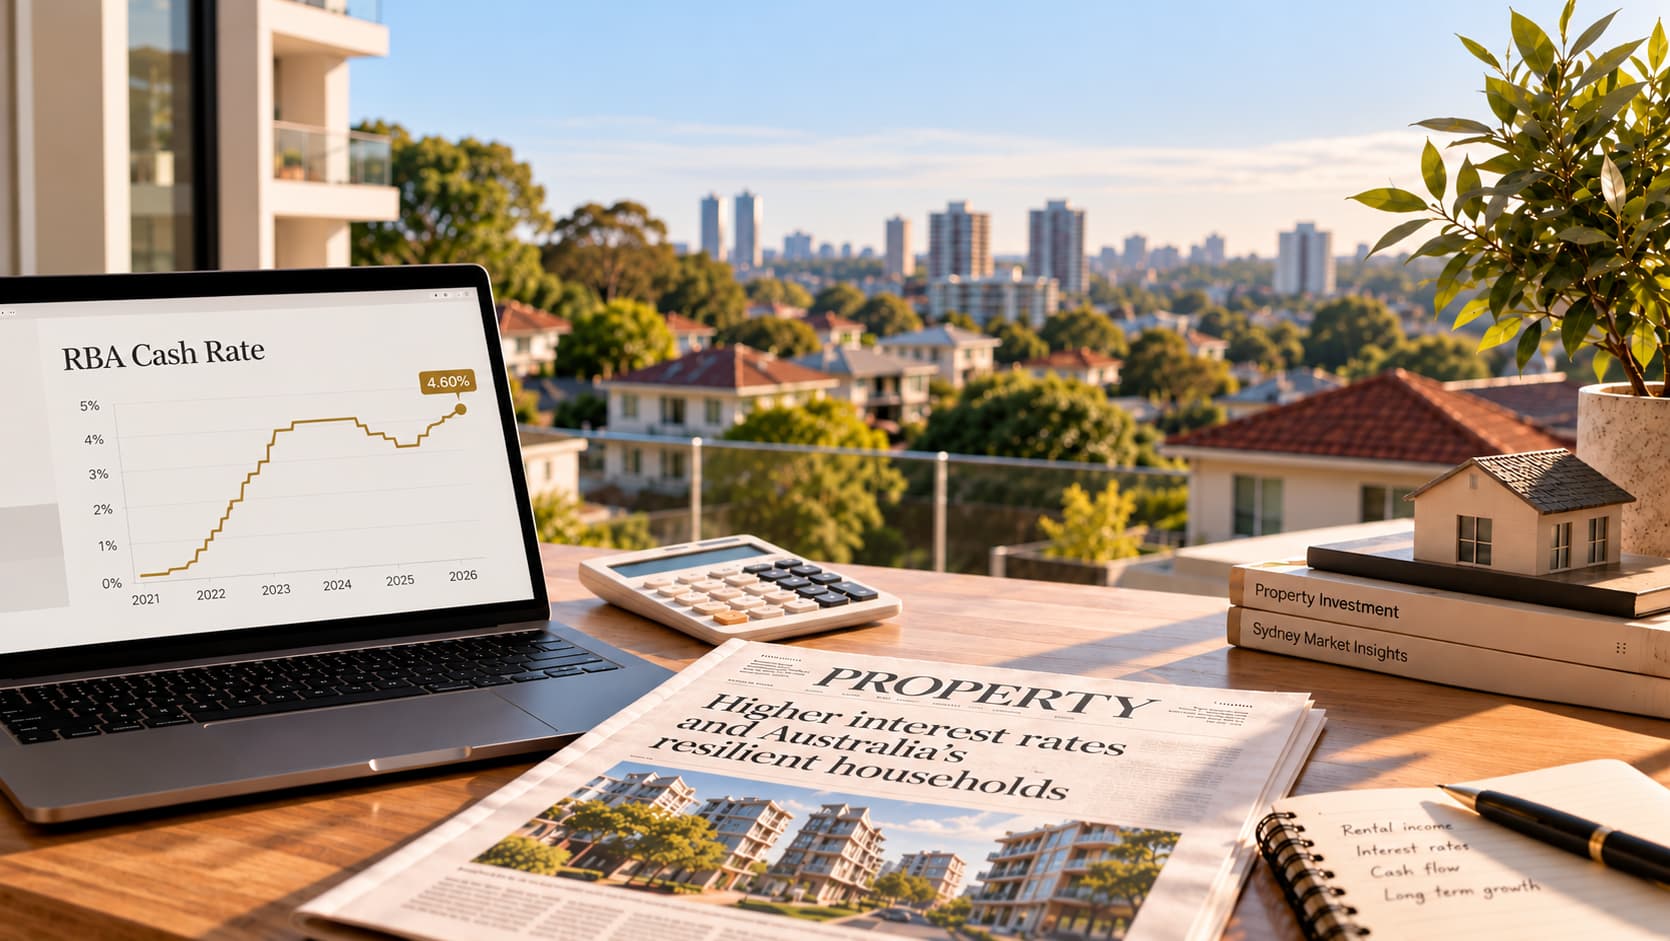
A higher-for-longer scenario would keep financing costs material for borrowers whose loan rates remain elevated. It could also leave less room for unexpected repairs or a leasing gap. That is a planning scenario, not YAY predicting the next RBA move. Loan terms, refinancing options and individual circumstances determine the actual exposure.
A landlord cannot assume a higher mortgage bill will be recoverable through rent. Prospective tenants compare alternatives; existing tenants face their own budgets. Asking above the market may prolong vacancy, while seeking the highest advertised rent can obscure the annual income lost between tenancies. The useful measure is sustainable net income across the year.
Review the property’s cash flow using today’s loan payments, realistic rent, recurring ownership costs and a maintenance allowance. Then examine a longer vacancy or a more expensive repair. This shows where reserves may need attention without depending on a rate-cut timetable or forecasting Sydney price growth.
YAY’s perspective: protect the income you can influence
Start with rental positioning. Review genuinely comparable homes, their condition and competing availability before setting an asking rent. A Rental Appraisal can help frame that discussion. Revisit the campaign when enquiry or applications suggest the proposition needs adjustment, rather than letting an initial target become a fixed expectation.
Put vacancy into the same decision. Compare a proposed rent difference with the income forgone while the property is empty, plus any reletting costs. Our Vacancy Cost Calculator helps owners explore their own assumptions. It is a planning aid, not evidence of future vacancy or a promise that any price will secure a tenant.
Tenant retention deserves similar attention. Clear communication, timely repairs and a well-maintained home give a satisfactory tenancy reasons to continue. Consider the cost and disruption of a changeover when discussing rent, while observing the applicable tenancy rules. Retention should support a sustainable tenancy for both parties.
Finally, plan maintenance before a failure forces an urgent decision. Separate necessary work from optional improvements, obtain suitable quotes and keep a realistic reserve. Our approach to Property Management connects leasing, tenant communication and maintenance with the owner’s income priorities.
The broader economy may be more resilient than an indebted owner feels. That tension is precisely why disciplined property management matters. A sound rental plan should remain workable if borrowing costs stay elevated, and leave the owner better prepared if conditions improve.