When property prices fall and borrowing costs remain high, the greatest risk for landlords may not be declining property values — but losing the financial flexibility to hold on.
Property markets move in cycles. Periods of strong growth are often followed by slower conditions, changing buyer sentiment and, sometimes, falling prices.
For Sydney property investors, a downturn raises an uncomfortable question: should you hold your investment property, reduce your exposure or sell before conditions deteriorate further?
There is no universal answer. Every investment property has different rental prospects, financing arrangements and holding costs. Every landlord also has a different financial position.
However, one principle applies across most market cycles: the ability to hold an asset through difficult conditions can be just as important as the asset itself.
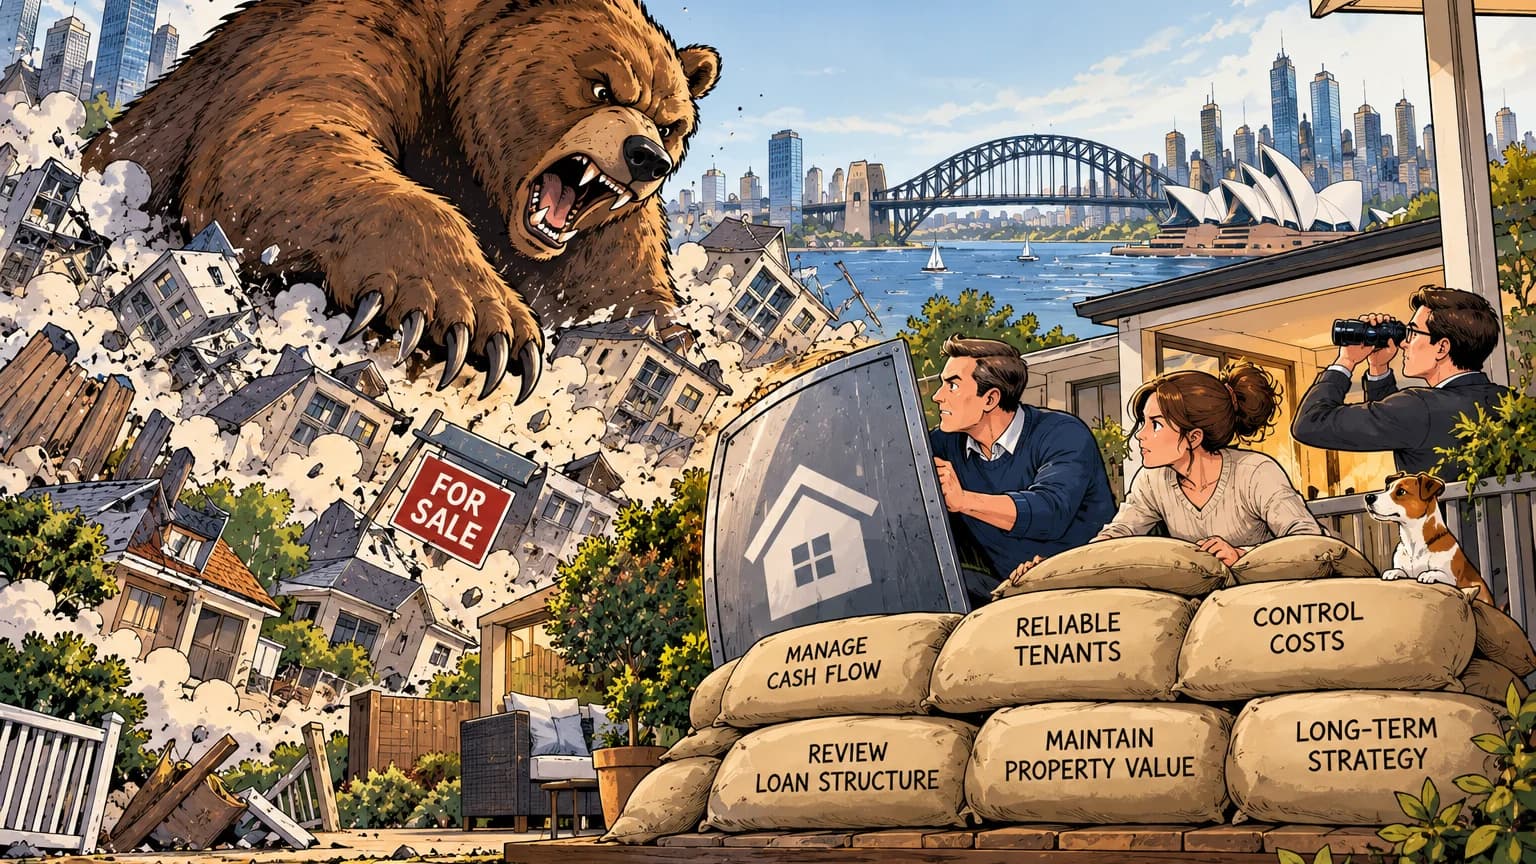
Rather than attempting to predict when the Sydney property market will bottom, landlords may be better served by focusing on the factors they can control.
Protect cash flow before it becomes a problem
A falling property valuation does not automatically create an immediate cash expense. Negative cash flow, however, can become a serious problem when household finances are already under pressure.
Rental income should never be confused with investment profit.
Mortgage interest, strata levies, council rates, insurance, property management fees, repairs and vacancy periods all affect the real cost of holding an investment property.
A useful exercise is to stress-test the property against several scenarios: higher interest rates, an unexpected repair, a prolonged vacancy or a temporary reduction in household income.
Landlords who maintain adequate financial buffers are generally better positioned to make decisions on their own terms rather than under financial pressure.
A reliable tenant can be worth more than a higher asking rent
In a challenging market, increasing rent may seem like the most straightforward way to offset higher ownership costs.
But the highest advertised rent is not necessarily the most profitable outcome.
Consider a property currently renting for $800 per week.
If the landlord holds out for an additional $30 per week but the property remains vacant for three weeks, the immediate rental loss is $2,400.
Even if the property subsequently leases at $830 per week, it would take 80 weeks of additional rent to recover that vacancy loss, before accounting for advertising and other reletting expenses.
This does not mean landlords should avoid reasonable rent increases.
It means rental decisions should reflect genuine market demand, comparable properties, tenant quality and the financial consequences of vacancy.
A reliable tenant who pays on time, looks after the property and intends to stay can provide meaningful stability during uncertain conditions.
All rent adjustments must also comply with applicable NSW residential tenancy requirements.
Control maintenance costs without compromising the asset
When finances tighten, reducing unnecessary expenditure is sensible.
However, postponing essential maintenance can create significantly larger problems later.
Water leaks, waterproofing failures, electrical safety concerns and other defects can become more expensive if left unresolved.
A disciplined maintenance strategy distinguishes between essential repairs, improvements that support rental performance and discretionary cosmetic upgrades.
Safety, legal compliance and urgent repairs should remain priorities. Improvements that materially improve tenant appeal or reduce future maintenance costs deserve consideration.
Purely cosmetic projects may be deferred when financial resources are limited.
Good property management is not simply about spending less. It is about spending appropriately, obtaining reliable evidence and preventing avoidable costs.
Review financing before financial pressure escalates
Highly leveraged property investors are particularly sensitive to interest-rate movements.
For illustration, a one-percentage-point increase in the interest rate on an unchanged $800,000 loan balance represents approximately $8,000 in additional annual interest.
That increase can materially affect an investment property's cash flow.
Landlords should periodically review their financing arrangements, including interest-rate competitiveness, offset account use and available refinancing options.
Importantly, falling property valuations may make refinancing or accessing equity more difficult.
Discussing options with a lender or qualified mortgage broker before difficulties arise may preserve choices that become less accessible later.
Holding or selling should be a financial decision, not an emotional one
Some investors believe that a property loss does not matter until the property is sold.
While market fluctuations do not necessarily require immediate action, this approach can overlook the ongoing cost of holding an unsuitable investment.
If an investment property consistently produces losses that the owner can no longer comfortably support, holding indefinitely may not be the best decision.
Conversely, a property with stable rental demand, manageable debt and a sound long-term investment rationale may remain worth holding despite a temporary decline in market value.
The relevant question is not simply what the property was worth at its peak.
It is whether holding that property from today remains consistent with the owner's financial objectives, risk tolerance and available resources.
Holding should be a deliberate decision, not an unwillingness to recognise a loss. Selling should be a considered strategy, not a forced response to financial distress.
A downturn can also be a time to reassess your portfolio
Not all Sydney investment properties will respond to weaker market conditions in the same way.
Local rental demand, building quality, strata expenses, maintenance requirements, transport accessibility and neighbourhood supply can all influence long-term performance.
A market downturn may be an opportunity to identify which properties deserve continued investment, which require improvement and which no longer fit the owner's strategy.
The aim is not necessarily to expand or reduce a portfolio. It is to make sure each property still has a clear purpose.
YAY Perspective: Surviving the winter is about preserving your options
No one can consistently predict the exact bottom of a property market.
For Sydney landlords, the more practical objective is to avoid becoming a forced seller at the worst possible time.
Reliable rental income, sensible tenancy decisions, proactive maintenance and adequate financial reserves can help protect that flexibility.
Professional property management becomes particularly valuable when conditions are difficult — not because it can eliminate market risk, but because it can help landlords manage the risks within their control.
The most important thing in a property downturn is not knowing exactly when spring will arrive. It is making sure you can afford to wait for it.
If you are reviewing the performance of your Sydney investment property, a property-specific rental appraisal and holding-cost review can be a useful starting point.
General information only. This article does not constitute personal financial, taxation, legal or credit advice. Seek appropriate professional advice before making investment, financing or sale decisions.